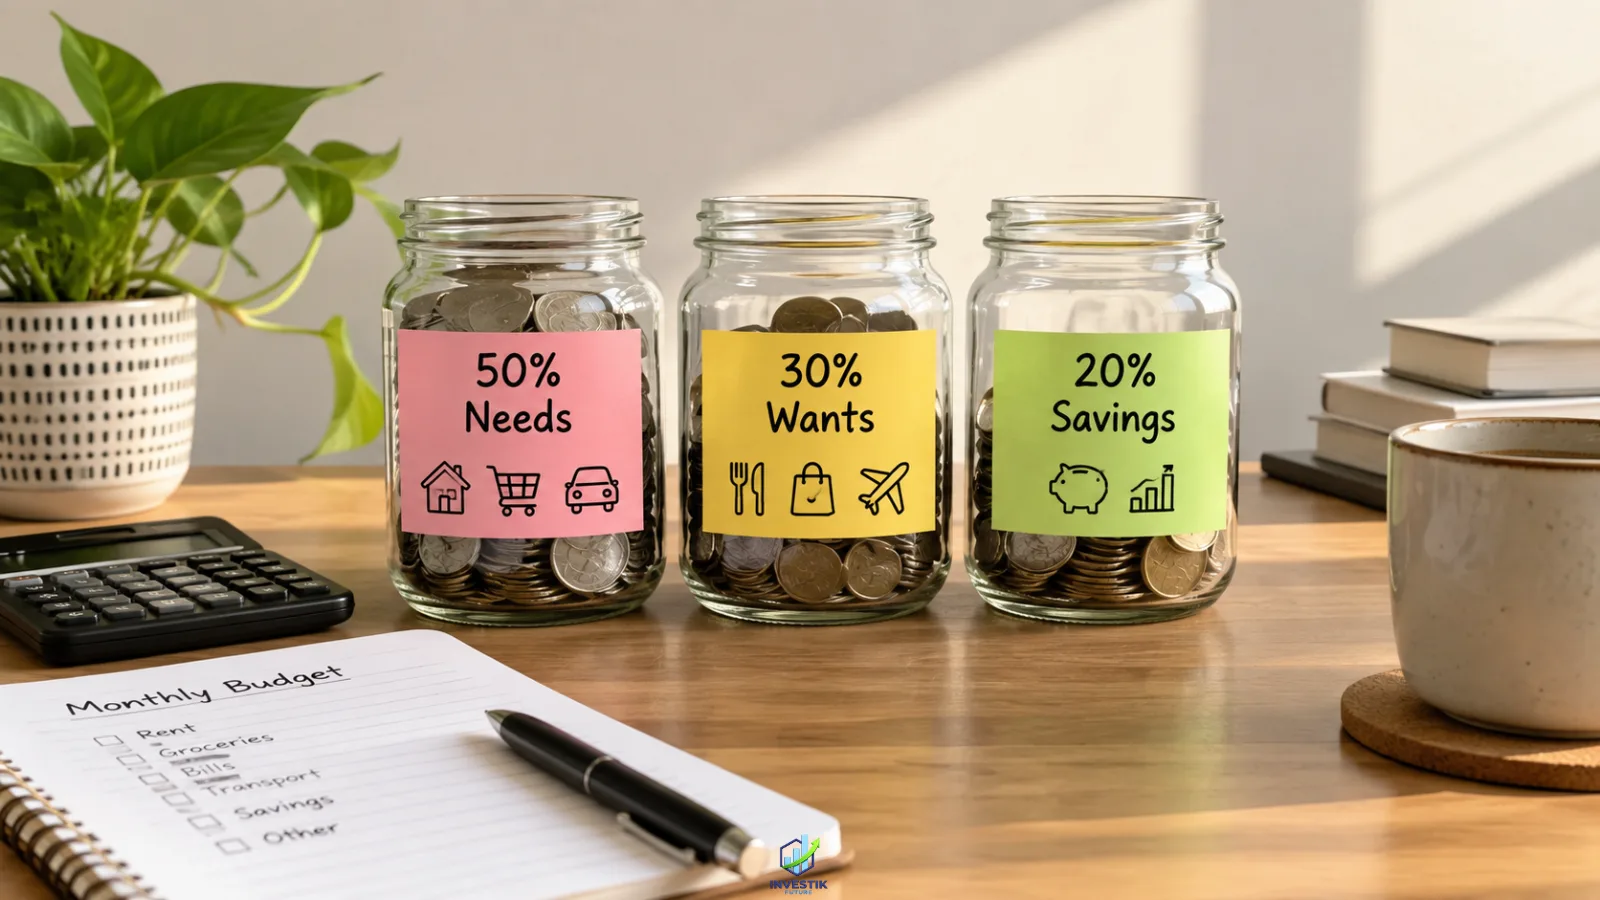

The 50/30/20 budget rule is a simple way to divide your monthly income into three parts. Half goes to needs, 30% goes to wants, and 20% goes to savings and debt repayment.
The rule is easy to follow because you don’t need a complicated spreadsheet or any financial expertise to get started. You take your monthly income, do a little maths, and get a rough idea of how much to spend on what.
It is not a strict rule, and it will not fit every household. But it gives you a clear place to start.
The article explains the 50/30/20 budget rule, showing how to divide monthly income between needs, wants, and savings or debt repayment. It also covers practical salary examples and how to adjust the rule for different situations in India.
What Is the 50/30/20 Budget Rule?
The 50/30/20 budget rule is a budgeting framework. It asks you to sort your spending into three buckets. It is not an official financial rule, and no government or regulator prescribes it.
50%: Needs
These are expenses you cannot easily skip. For example:
- Rent or home maintenance
- Groceries
- Electricity, water, and gas bills
- Mobile and internet bills you need for daily life
- Transport to work or college
- Insurance premiums
- School fees for children
30%: Wants
These are things you enjoy but could live without:
- Eating out and ordering food online
- Shopping for clothes, gadgets and accessories
- Movies, OTT and music subscriptions
- Weekend trips and holidays
- Hobbies
- Other non-essential purchases
20%: Savings and Debt Repayment
This is the money you set aside for your future self. It can include:
- An emergency fund
- Savings for a goal, such as a trip, a wedding, or a down payment
- Investments
- Extra payments towards eligible debt, such as a credit card balance or a personal loan
How Does the 50/30/20 Rule Work?
The calculation is easy. Start with the money that actually reaches your bank account after tax and deductions. Use your monthly take-home income rather than your CTC. Then work out 50%, 30%, and 20% of that amount.
Say your monthly take-home income is ₹50,000.
- Needs: 50% of ₹50,000 = ₹25,000
- Wants: 30% of ₹50,000 = ₹15,000
- Savings/debt repayment: 20% of ₹50,000 = ₹10,000
That means ₹25,000 is for rent, food, bills, and other essentials. Up to ₹15,000 is for things you enjoy. And ₹10,000 goes to savings or debt repayment.
If your income changes every month, use the amount you can rely on in a normal month. You can also use your average income from the last few months.
50/30/20 Rule Examples for Different Salaries
Here is how the split looks at different monthly take-home incomes.
| Monthly take-home income | 50% Needs | 30% Wants | 20% Savings/Debt |
| ₹30,000 | ₹15,000 | ₹9,000 | ₹6,000 |
| ₹40,000 | ₹20,000 | ₹12,000 | ₹8,000 |
| ₹50,000 | ₹25,000 | ₹15,000 | ₹10,000 |
| ₹75,000 | ₹37,500 | ₹22,500 | ₹15,000 |
| ₹1,00,000 | ₹50,000 | ₹30,000 | ₹20,000 |
These are only starting points. Your own numbers may look quite different, and that is fine.
What Counts as a Need?
A simple test: if skipping the expense would cause a real problem in your daily life, it is probably a need.
Common needs in India include:
- Rent, or the maintenance and property tax on a house you own
- Groceries and cooking gas
- Electricity, water, and society maintenance
- Basic mobile and internet plans
- Travel to work, such as the metro, a bus pass, or fuel for your bike
- Health and life insurance premiums
- Children’s school fees
- Medicines you take regularly
The same expense can be a need for one person and a want for another. It depends on the situation.
- Your daily metro or bus fare to the office is a need. Booking a cab every day when a cheaper option exists is partly a want.
- A basic mobile plan is a need. An expensive phone upgrade is a want.
- Groceries are a need. Ordering in three times a week is a want.
- If you work from home, a good internet connection is a need. If you don’t, a faster plan just for streaming is a want.
You don’t need to be perfect here. If you cannot decide, split the expense. Count the basic part as a need and the extra part as a want.
What Counts as a Want?
Wants are the things that make life more enjoyable but are not essential. Spending on them is not wrong. A budget with no room for fun rarely lasts more than a few weeks.
Some common examples:
- Restaurant meals, cafes, and food delivery
- Clothes and shoes beyond what you actually need
- Movie tickets, concerts, and games
- OTT and music subscriptions
- Weekend getaways and holidays
- Salon visits, gym memberships you rarely use, and hobby supplies
- Gadgets, gifts and impulse buys
The point is only to see how much of your money goes to things you could pause if you had to. That is useful to know, especially in a month when money gets tight.
What Comes Under the 20%?
This bucket is for your future. It covers two things: savings and debt repayment.
- Emergency fund: Money set aside for sudden expenses like a medical bill or a job gap.
- Goal-based savings: Money for something planned, like a trip, a wedding, or a new vehicle.
- Investments: Money you put into different investment options based on your own goals and comfort with risk.
- Debt repayment: Extra payments towards debt, such as a credit card balance or a personal loan, so it gets cleared sooner.
How you split the 20% is up to you. Someone with no savings may put most of it into an emergency fund first. Someone with a high-interest credit card balance may focus on paying that down. Others may divide it across several goals.
EMIs can be classified differently depending on how you build your budget. You may treat a necessary loan payment as a need, while additional payments toward debt can be counted in the 20% savings and debt-repayment category. The important thing is to use the same approach consistently.
Can You Follow the 50/30/20 Rule in India?
For many households, it will need some adjusting. The 50/30/20 split may not always fit Indian households because living costs, family responsibilities, and income levels vary widely.
Here are some common situations.
High rent in big cities: In cities like Delhi, Mumbai, or Bengaluru, rent alone can take a big share of income. Add groceries, transport, and bills, and needs can cross 50% quickly.
EMIs: A home loan, car loan, or education loan can take a large chunk of your monthly income. This changes the split significantly.
Supporting family: Many people send money to parents or support siblings. This is a regular, important expense, and it may reasonably count under needs.
Children’s education: School fees, tuition and books can be a big and rising cost for parents.
Irregular income: Freelancers, small business owners, and commission-based earners don’t get the same amount every month. Planning around a fixed percentage is harder.
Lower salaries: When income is lower, essentials take up a larger share, and there is less room for wants or savings.
Rising costs: Groceries, fuel, rent, and school fees tend to go up over time. A split that works this year may need a rethink next year.
None of this means the rule is useless. It means the percentages are a guide, not a target you must hit.
What If Your Expenses Don’t Fit the 50/30/20 Rule?
Most people’s budgets won’t match 50/30/20 exactly. Here are a few examples for a ₹50,000 monthly take-home income.
| Situation | Needs | Wants | Savings/Debt |
| Rent and family costs are high | 60% = ₹30,000 | 20% = ₹10,000 | 20% = ₹10,000 |
| Fixed costs are very high | 70% = ₹35,000 | 10% = ₹5,000 | 20% = ₹10,000 |
| Living costs are low | 40% = ₹20,000 | 30% = ₹15,000 | 30% = ₹15,000 |
In the first case, needs are higher, so wants shrink to keep savings at 20%. In the second, there is very little room left for wants. In the third, low essential costs leave more room for savings than 20%.
These examples show how the percentages can change when essential expenses are higher or lower. The right split depends on the person’s income, expenses, and financial priorities.
If your needs are well above 50%, look at them one by one. Is anything higher than it needs to be? If nothing can change right now, adjust the other two buckets and revisit the numbers every few months.
Is the 50/30/20 Budget Rule Right for Everyone?
Not necessarily. It works well as a starting point, but it has limits.
Where it helps:
- It is easy to remember and easy to calculate.
- It works for people who have never made a budget.
- It shows quickly whether one category is taking too much.
- It builds the habit of setting money aside before it is spent.
Where it falls short:
- The percentages are the same for everyone, but living costs and responsibilities are not.
- It does not account for large EMIs, family support, or irregular income very well.
- The line between needs and wants can be blurry.
- At lower incomes, 50% for needs may simply not be enough.
So it is best seen as a simple tool for organising your money. Use it as a first draft, then change it to match your real life.
Key Takeaway
The 50/30/20 budget rule is a simple framework. It splits your income into needs, wants, and savings or debt repayment. The percentages are only a starting point, and you can change them based on your income, city, loan payments, and family responsibilities. What matters most is understanding where your money goes each month.
FAQs
What is the 50/30/20 budget rule?
It is a budgeting framework that divides your monthly take-home income into three parts. 50% goes to needs, 30% to wants, and 20% to savings and debt repayment. It is a guideline, not an official rule.
What is included in the 50% needs category?
Needs are essential expenses such as rent, groceries, utility bills, transport to work, insurance premiums, school fees, and basic phone and internet costs. A necessary loan payment can also be counted here, depending on how you build your budget.
What counts as wants in the 30% category?
Wants are things you enjoy but could pause if needed. Examples are eating out, shopping, OTT subscriptions, movies, holidays, and hobbies.
Does the 20% include investments?
It can. The 20% is for savings and debt repayment, and investments are one way people use it. You can also use it for an emergency fund, other savings goals, or paying down debt. How you split it is your decision.
Can I change the 50/30/20 rule?
Yes. The percentages are meant to be adjusted. If your rent or EMIs are high, your split may look more like 60/20/20 or 70/10/20. If your expenses are low, you may be able to save more.
ARN Disclosure: Investik Future is an AMFI-registered Mutual Fund Distributor. ARN-341107 — Verify on AMFI ↗. Komal Thakur is the content author and digital marketer; the ARN registration belongs to Investik Future, not to the author personally.